Pistachio supply tightens, freight climbs; plenty in hazelnuts and coffee
June was the month in which new-season crop estimates began to take shape. Forecasts of a more than one-third drop in world pistachio output and strong US shipments to Türkiye and MENA supported prices, while expectations of a large hazelnut crop and a record Brazilian coffee harvest weighed on them; container freight climbed to its highest level since September 2024.
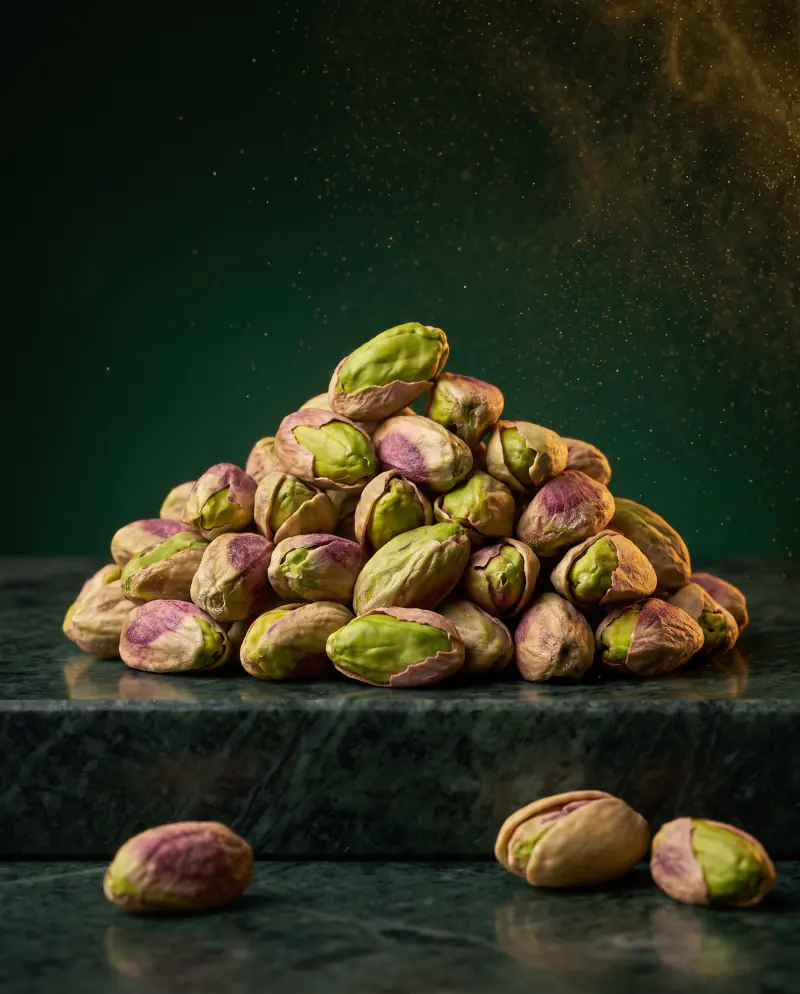
Pistachio supply set to shrink sharply next season
According to the INC forecast (4 June), world pistachio output will fall 36.4% in 2026/27 to about 701,000 t: the US 350,000 t (-51.6%) and Iran 130,000 t (-42.2%), while Türkiye rises 36.5% to 156,400 t. ACP data for May showed US shipments up 14.1% at 97.1 million lb, with exports up 25.7% and the season total reaching 1.025 billion lb (+18.3%). Early estimates put the new California crop at roughly half of the record 2025 harvest.
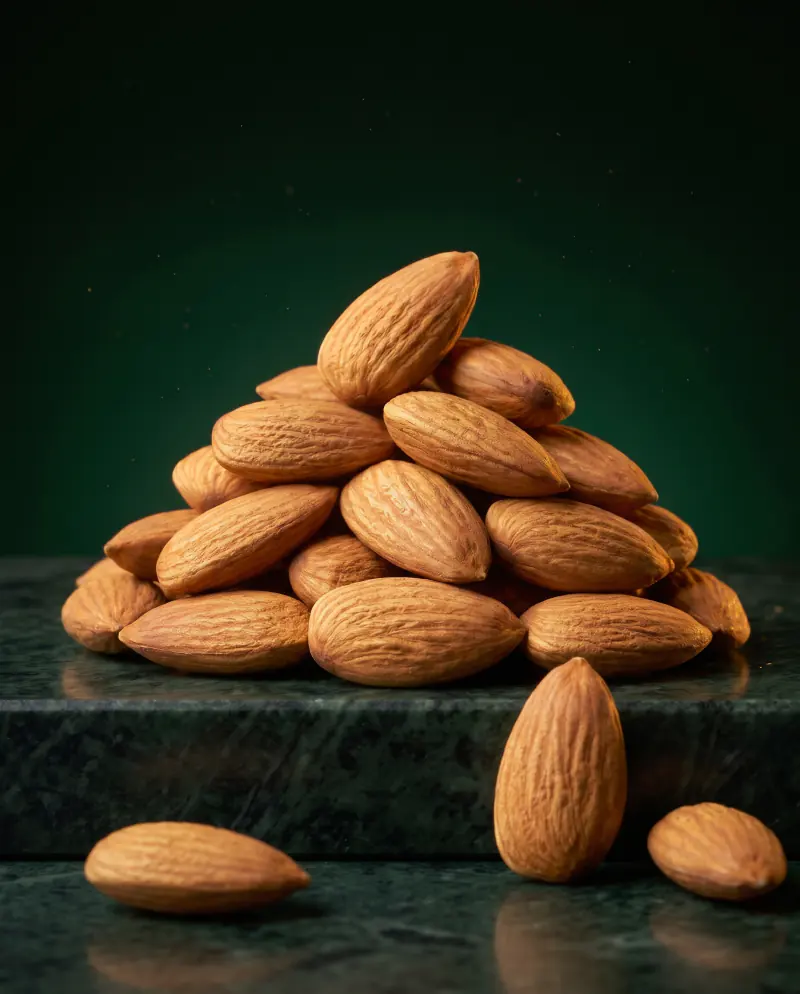
Strong Turkish demand for California almonds; prices firm
In the Almond Board’s May report, released on 11 June, California shipments rose 2.6% to 217.4 million lb and exports increased 5.2%; shipments to Türkiye rose 126% and to Morocco 217%, while those to the UAE fell 74%. New-crop sales reached 92 million lb and prices firmed slightly, while in Spain frost losses were reported in organic orchards in Granada and Almería.
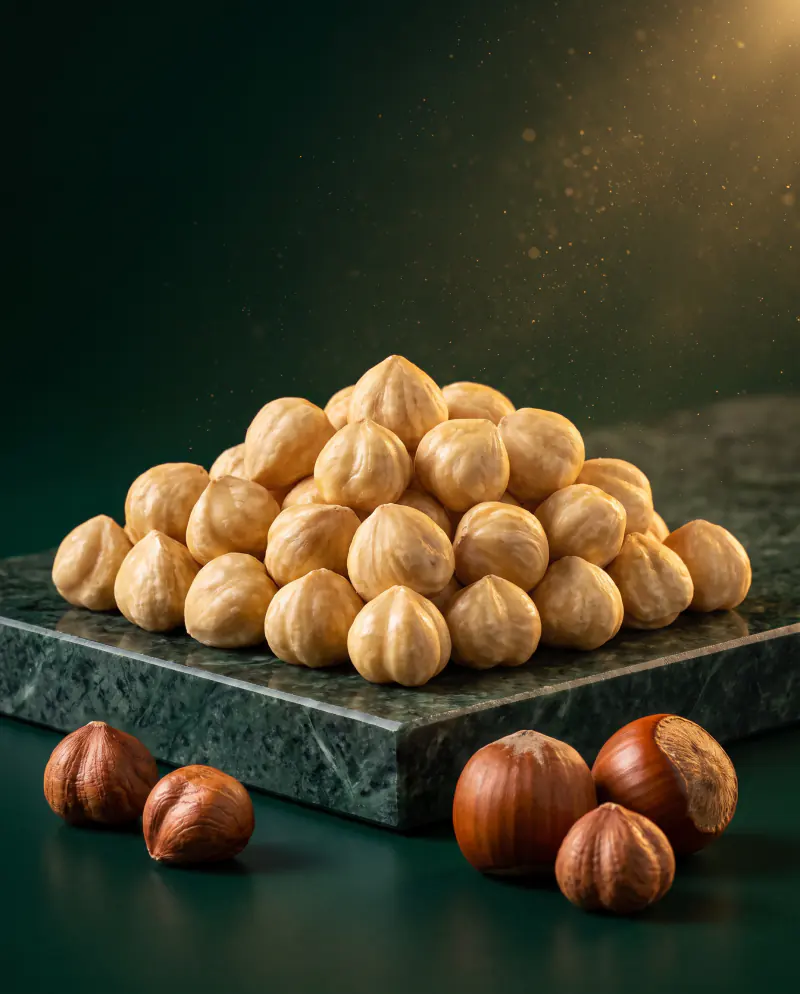
Sector estimates put Türkiye’s 2026/27 hazelnut crop at about 810,000 t, well above 2025/26. On that outlook, FOB Istanbul natural kernels fell 2.3% on the week to about €6.82/kg for 11–13 mm and €7.35/kg for 13–15 mm as of 29 June. Export volumes in the first months of the year were down more than 30% year on year, while TMO purchase prices continue to act as a floor for growers.
€6.82/kgNatural kernels 11–13 mm, FOB Istanbul, 29 June
Sources (1)
Commodity Board — 2026/27’te büyük rekolte beklentisiyle Türk fındık fiyatlarında gevşeme 2026-06-30
Brazil eyes record coffee crop as rain slows harvest
In early June USDA FAS forecast Brazil’s 2026/27 coffee output at a record 71.9 million bags (+14.1%), with arabica up 25% to 47.5 million bags. According to Cecafé, May exports rose 3.6% to 3.089 million bags while revenue fell 16% to US$1.05 bn. ICE arabica traded around US$2.50/lb on 5 June, near its lowest since November 2024, then rose to nearly US$2.78/lb on 18 June, its highest since mid-May, as rain delayed the harvest (44% complete by 24 June versus 51% a year earlier).
71.9 mn bagsUSDA: Brazil 2026/27 crop forecast (+14.1%)
Vietnam exported about 74,100 t of cashew in May, up 7.7% in volume and 8.2% in value on April, though year-to-date volume remains slightly below last year. In mid-June Vietnam WW320 FOB held at about €6.27/kg and WW240 at €7.11/kg, with India W320 near €6.33/kg. Towards the end of the month, monsoon rains and a weaker rupee raised raw cashew costs in India and lent mild support to offers.
≈€6.27/kgVietnam WW320 FOB, mid-June
Sources (2)
Commodity Board — Cashew kernels edge higher as India monsoon starts and Vietnam exports stay firm 2026-06-14
Commodity Board — Cashew kernels edge higher as monsoon rains hit India and demand holds 2026-06-21
US in-shell walnut exports surge on Türkiye and MENA
Season to date, US in-shell walnut shipments to MENA rose from 37 to 183 million lb (+395%), with the UAE, Algeria, Lebanon, Iraq and Morocco contributing, while shipments to Türkiye roughly quintupled. Chinese kernel offers rose by US$70–160/t in recent weeks. California prices nonetheless remain depressed: although bearing acreage has fallen to about 376,000 acres, tree loads still point to a large 2026 crop.
+395%US in-shell walnuts to MENA, season to date
Sources (2)
Commodity Board — American in-shell walnuts surge on export boom to Turkey and MENA 2026-06-26
Commodity Board — Walnuts under pressure: big California crop meets fragile demand 2026-06-19
Turkish sultana raw material traded at TRY 80–85/kg in mid-June; growers are holding stock and a TMO intervention is expected for the new season, although prices have not yet been announced. Exports from September 2025 to mid-June reached about 110,600 t, below 124,400 t a season earlier. On 25 June Type 9 FOB was steady at about €2.74/kg; vineyards are in very good condition, with hail the main risk.
TRY 80–85/kgTurkish sultana raw material, mid-June
Sources (2)
Commodity Board — Tight raisin supply meets rising Turkish support prices: window for buyers 2026-06-17
Commodity Board — Turkish raisin prices hold firm as weather stays favourable but freight costs climb 2026-06-25
Old-crop stocks in Xinjiang are being cleared and the 2026 crop is expected in early September; Shine Skin plantings are slightly below last year. On 11 June FOB Beijing Shine Skin AA stood at €3.35/kg and GWS AA at €2.93/kg, both up €0.03 on the week. Prices held on a high, stable plateau through late June, with July–August heat the main risk.
€3.35/kgShine Skin AA, FOB Beijing, 11 June
Sources (2)
Commodity Board — China pumpkin seeds: low stocks, strong prices ahead of 2026 new crop 2026-06-12
According to American Pecan Council April data published in early June, shipments fell 21.5% year on year to 18.8 million lb, bringing the season total to 247.0 million lb (-10.8%). Inventory stood at 262.7 million lb, 4.6% higher year on year, commitments were down 10.1%, and the net position reached +65.9 million lb, the highest of the season. Sources say supply no longer limits trade and that demand and shipment pace will set the direction.
Peanut plantings drop sharply in the US and Brazil
According to USDA NASS’s 30 June report, US peanut plantings fell 22% to 1.53 million acres; in Georgia, the largest producer, area was also down 22%, with 63% of the crop rated good to excellent (72% a year earlier). Brazil’s planted area was reported down 30%. Near-term supply is nonetheless comfortable: US farmer-stock prices eased to about US$0.23/lb in late May, while Argentine 40/50 blanched offers held firm at US$1,450–1,500/t.
Brazil nuts firm despite a much larger crop outlook
Estimates cited from Mundus Agri put 2026/27 in-shell Brazil nut output about 80% above a short previous season, led by Bolivia with contributions from Peru and Brazil. Even so, medium-size prices in the Netherlands (FCA Dordrecht) firmed slightly in late June. Higher South America–Europe freight and steady EU demand are supporting prices.
≈ +80%Expected 2026/27 in-shell Brazil nut output
Sources (1)
Commodity Board — Brazil nuts edge higher in Dordrecht as freight costs bite 2026-06-27
Kenya’s raw-nut export ban drags macadamia prices down
With Kenya’s ban on raw macadamia exports still in place, farm-gate prices fell to as little as KES 40/kg, from about KES 150/kg in 2023 when the ban was suspended (The Star, 8 June). A ministry team found more than 18,000 t without a market, while growers’ association NUTAK puts the stock at about 25,000 t; the ministry has signalled a review of the ban. A strong 2026 crop and weak global demand have led some processors to cut throughput or close.
KES 40/kgKenya macadamia farm-gate price (2023: ~150)
Sources (2)
The Star (Kenya) — Relief for macadamia farmers as ministry signals review 2026-06-08
Commodity Board — Kenyan macadamias under pressure as local glut collides with weak global demand 2026-06-17
Record global sunflower crop seen; Ukrainian prices flat
According to Oil World’s preliminary forecast, world sunflower output will rise from 57.5 to 63.3 million t in 2026/27; Ukraine’s sown area stands at 4.86 million ha and some analysts expect a crop of 13–14 million t (UkrAgroConsult, 22 June). With limited old-crop supply, Ukrainian purchase prices for 50%-oil seed held steady at UAH 32,400–33,500/t. In sunflower oil, demand prices at Black Sea ports were US$1,320–1,325/t DAP while October offers to Türkiye stood at US$1,200–1,250/t, pricing the new crop lower.
63.3 mn tWorld sunflower output 2026/27, Oil World preliminary
Sources (1)
UkrAgroConsult (GrainTrade) — Forecasts of a record sunseed harvest in MY 2026/27 do not yet affect prices in Ukraine 2026-06-22
Logistics and freight Rising
Container freight at its highest since September 2024
On the Drewry WCI, Shanghai–Genoa rates for a 40ft container rose from US$5,089 on 4 June to US$5,759 on 25 June, and the composite reached US$4,166, its highest since September 2024. Red Sea diversions continue, and a US–Iran ceasefire eased Strait of Hormuz transit risk, though Drewry describes the situation as fragile. The CBRT held its policy rate at 37% on 11 June; USD/TRY rose from 45.96 to 46.67 over the month.